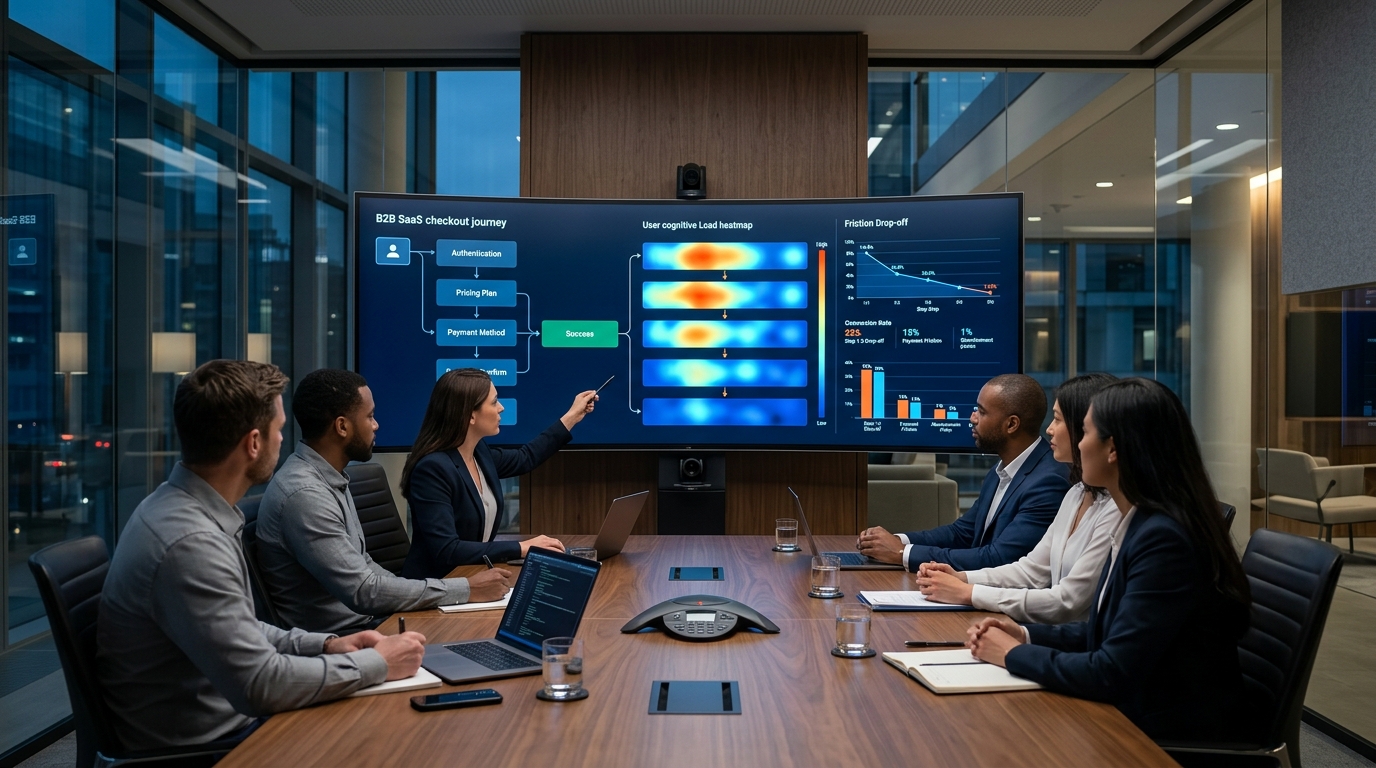
Closing a $24,000 annual B2B software agreement only to have the procurement lead abandon the final checkout screen is one of the most agonizing failure modes in enterprise technology. Yet across corporate software, enterprise checkouts suffer from catastrophic drop-off rates because product teams treat corporate billing like an ordinary consumer e-commerce shopping cart. When a vice president or procurement director reaches a payment portal with a corporate purchasing card, they face mandatory personal address fields, broken VAT/tax validation errors, and zero native invoicing pathways.
Enterprise buyers do not purchase software the way individuals buy sneakers. They are bound by corporate compliance, purchase order (PO) workflows, departmental cost-center routing, and strict accounting reconciliation guidelines. When your checkout flow forces a corporate buyer into an unforgiving 16-digit credit card form without automated invoice generation or tax exemption handling, the deal stalls in finance committees—often permanently.
Why Enterprise Checkouts Drop 6-Figure Deals
The core disconnect in B2B checkout design lies in cognitive misalignment. In consumer e-commerce, speed and friction eradication are everything: 1-click Apple Pay wins every time. In enterprise B2B transactions, however, the individual typing the details is rarely spending their own personal capital. They are an agent acting on behalf of an organization, and their chief priority is administrative compliance, internal audit proofing, and expense justification.
When an enterprise payment gateway triggers a generic “Card Declined – Contact Your Bank” message, it rarely means the enterprise lacks credit. It almost invariably means the billing zip code entered by the IT manager does not match the corporate headquarters treasury address registered with the corporate American Express account. Standard consumer checkouts fail to provide contextual helper copy for corporate cardholders, forcing the buyer to abandon the flow and search for alternative enterprise vendors.
| Checkout Dimension | Consumer Checkout Design | Enterprise B2B Checkout Requirement | Conversion Impact |
|---|---|---|---|
| Payment Options | Cards, Apple Pay, PayPal, Klarna | Corporate Cards, ACH/SEPA, Net-30 Invoicing, Wire PO | Prevents 42% of corporate drop-offs |
| Tax & Compliance | Standard local sales tax added at end | Real-time VAT/GST validation & tax-exempt ID upload | Eliminates cross-border accounting blocks |
| Billing Address | Tied to personal cardholder home | Separate Treasury Entity Address vs Billing Contact | Slashes AVS bank decline errors by 65% |
| Audit & Invoicing | Basic email receipt link | W-9 form download, SOC2 badge, formal PDF tax invoice | Accelerates finance committee sign-off |
| Seat Scaling | Fixed single-unit pricing | Dynamic seat tiers with prorated mid-cycle co-terming | Eliminates checkout pricing confusion |
The 4 Architectural Fixes for Enterprise Checkout Friction
To eliminate friction and capture high-yield B2B revenue, enterprise design teams must rearchitect their checkout infrastructure around corporate realities:
1. Implement Dual-Track “Card vs. Invoice” Splitting
Never lock multi-seat enterprise software behind a mandatory card capture field. Introduce an upfront modal or toggle that separates transactions under $5,000 from larger organizational contracts. For contracts exceeding standard credit limits, allow buyers to select “Generate Net-30 Invoice / Purchase Order”. The workflow should immediately provision the workspace on a verified corporate email domain while automatically dispatching a compliant PDF invoice to their accounts payable department.
When offering invoice billing, allow procurement leads to upload their official purchase order PDF directly onto the confirmation screen. Capturing their internal PO number, billing entity legal name, and accounts payable email automatically attaches these details to the generated invoice, allowing corporate controllers to approve payment without initiating endless email threads with your support team.
2. Decouple Treasury Card Address from License Administration
Corporate card decline rates exceed 28% on generic checkout forms because the user interface assumes the user sitting at the keyboard is the cardholder. B2B checkouts must explicitly separate the License Administrator Contact from the Corporate Treasury Billing Address. Providing a dedicated checkbox that states: “This is a corporate card registered to headquarters” instantly prompts the user to enter their finance team’s registered legal entity address, eliminating AVS rejection errors.
Furthermore, corporate cards frequently enforce departmental spending caps (e.g., $2,500 daily transaction limits). If a $10,000 annual charge fails, standard checkouts show an alarming red error banner that implies non-payment. High-converting B2B checkouts show an empathetic message: “Transaction exceeded card limit? Click here to split into quarterly installments or switch to automated ACH wire transfer.”
3. Inline Real-Time Tax Exemption and VAT Engine Integration
International corporate deals frequently stall when European or Canadian buyers see consumer sales tax added to their 5-figure enterprise software purchase. Incorporating real-time VIES VAT verification (via Stripe Tax or Paddle) allows enterprise procurement to input their corporate tax registration number directly on the checkout screen. When the system instantly verifies the VAT number and removes the tax line item with an explicit “Reverse Charge Applied – 0% VAT” notice, procurement friction evaporates.
For US buyers claiming non-profit, educational, or reseller tax-exempt status, provide an inline document upload field directly within the tax calculation block. Allowing the customer to upload their state tax exemption certificate and instantly receive provisional tax exemption status keeps the checkout moving rather than stalling the purchase for days.
4. Automated Compliance Dock (W-9, SOC 2, and Vendor Forms)
Before a corporate finance department releases payment for a software tool, their vendor onboarding policy requires a signed IRS W-9 (for US entities) or Certificate of Residency, alongside security compliance verification. Placing a discreet, expandable “Vendor Onboarding & Finance Package” link directly beneath the final checkout call-to-action—allowing one-click download of your W-9, banking wire instructions, and SOC 2 executive summary—removes the multi-week email chain between procurement and sales reps.
ACH Direct Debit vs. Credit Card Processing
Credit card interchange fees on enterprise transactions can silently bleed 2.9% to 3.5% of top-line software revenue. On a $50,000 corporate agreement, card processing fees cost your business $1,750 in pure processing waste. Integrating automated ACH Direct Debit (via Stripe Financial Connections or Plaid) caps processing costs at $5.00 per transaction while offering enterprise customers a direct bank transfer mechanism favored by treasury departments.
By offering an immediate 3% discount or an additional free user seat for selecting ACH Direct Debit over credit card payment, enterprise software companies incentivize corporate finance teams to choose the most cost-effective payment pathway, creating a win-win scenario that increases customer lifetime value and operating margins.
The Step-by-Step B2B Checkout Audit Checklist
- Audit Card Decline Logs: Review your Stripe or payment processor logs specifically for `card_declined` with reason codes `incorrect_zip` or `generic_decline` on corporate BIN numbers.
- Add Purchase Order Fields: Ensure an optional “PO Number / Cost Center Code” field is clearly visible on every checkout screen; finance teams require this for invoice matching.
- Test Mobile Corporate Approval: Many enterprise leaders approve quotes from their mobile phones via Slack or corporate email. Ensure the entire B2B checkout form renders smoothly without horizontally clipped input fields on mobile viewports.
- Display Security Guarantees: Position 256-bit TLS encryption, SOC 2 Type II compliance badges, and guaranteed SLA terms directly in the checkout summary sidebar to reassure risk-averse executives.
- Set Up Multi-Currency Invoicing: Ensure European and Canadian corporate buyers can choose between billing in USD, EUR, or CAD to prevent unexpected foreign exchange conversion fees from triggering internal audit red flags.